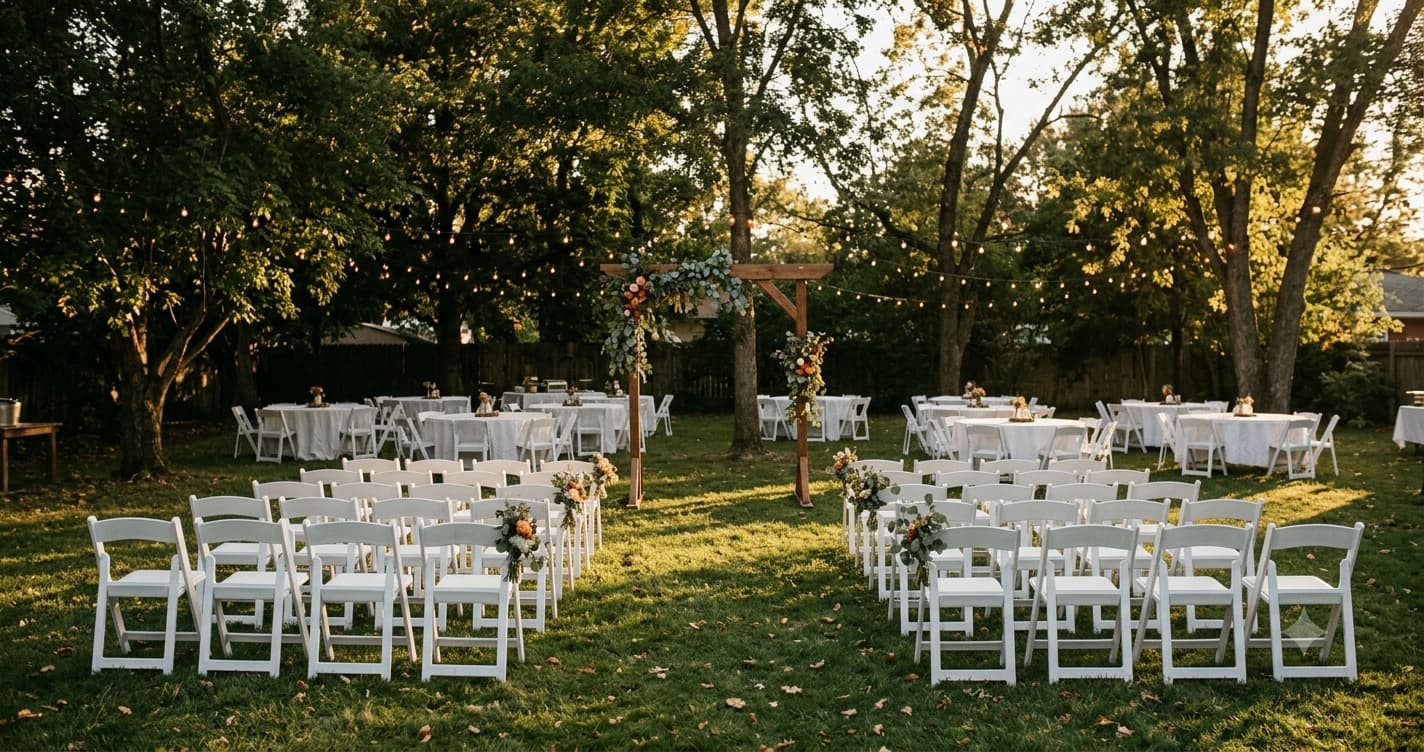
Nobody tells you this part: when you skip the venue, you also skip the venue's insurance. That protection you never thought about because someone else was carrying it? It's just gone, and it was never yours to begin with.
"It's just our backyard, why would we need this?"
Because "our backyard" is exactly the scenario liability insurance exists for. At a traditional venue, the venue's own policy sits behind you as a buffer, and the venue's staff has usually thought about tripping hazards, extension cord placement, and where 60 people can safely stand. In a backyard, none of that infrastructure exists — you built it this week out of rented tables, string lights, and a folding dance floor on grass that was fine until it rained Tuesday.
The two things that actually go wrong at private-property weddings, repeatedly: someone gets hurt (uneven ground, a fire pit, a dance floor that wasn't as level as it looked), or something gets damaged (a rental company's tent stakes through a sprinkler line, a spilled drink through hardwood that wasn't yours to begin with if you're at a rented Airbnb). Liability coverage is what stands between "unlucky accident" and "you personally covering someone's medical bill or a landlord's repair invoice."
Your homeowner's insurance is not a backup plan
This is the assumption that costs people the most: homeowner's and renter's policies are written for normal household risk, not for "60 people, a rented bar setup, and a DJ" risk. Most homeowner's policies either exclude commercial-adjacent gatherings entirely or cap liability well below what a serious injury claim could run. Call your insurer and ask directly if you're unsure — but plan as if the answer is no, because for most standard policies, it is.
The alcohol question gets bigger, not smaller, at home
At a licensed venue, the caterer or bartender usually carries their own liquor liability, and it covers the pouring. At a backyard wedding, if a family member is behind the bar or it's a stock-the-cooler-yourself setup, that liability sits with whoever's hosting — meaning you. Host liquor liability coverage is typically bundled into a standard wedding liability policy for exactly this reason, and at a home wedding, it's doing more work than it would anywhere else.
What it actually costs for a backyard setup
Roughly the same as any liability policy: $75–$190 for the standard $1 million in coverage, based on guest count and whether alcohol's involved. The full cost breakdown covers what else moves that number. If you're also worried about the wedding itself getting cancelled — a hurricane forecast, a sudden illness — that's the separate cancellation product, and for a lower-budget backyard wedding with fewer non-refundable deposits on the line, it's often the one couples skip while still buying liability.
The one number every quote form will ask for
Insurers size your liability quote around your guest count, and "somewhere between 50 and 80, I think" is not an answer that gets you an accurate price. If you're already collecting RSVPs digitally, that exact number is sitting in your dashboard — Eventic's RSVP tracking feature keeps every response in one place instead of scattered across texts and DMs, which makes the insurance-quote step considerably less annoying than guessing.
Rent the tent, borrow the chairs, DIY the flowers — just don't DIY the liability question. That's the one part of a backyard wedding where the shortcut isn't actually cheaper.
People Also Asked
Explore common questions related to this blog.
Smaller guest counts lower the liability premium somewhat, but the coverage still matters — the risk isn't guest count, it's the lack of a venue policy behind you at all. Twenty people on uneven grass with a fire pit is still a real exposure.
If it's not your own home — a family member's yard, a rented property — yes, most carriers let you add them as an additional insured the same way a venue would be added, and it's worth doing even if nobody asks.